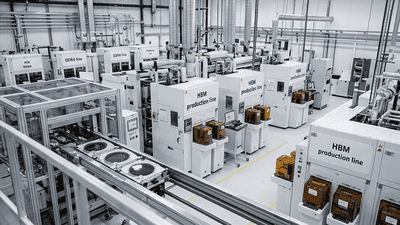
Between 2023 and 2026 the semiconductor industry witnessed a structural shift: a growing fraction of global DRAM wafer-equivalent capacity was repurposed for High-Bandwidth Memory (HBM) production. That reallocation—driven by hyperscaler commitments, higher ASP incentives, and strategic capex by major memory makers—has had a pronounced “crowding out” effect on commodity DRAM supply.
What “crowding out” means in this context
Crowding out describes the situation where resources—wafer starts, specialized process capacity, and skilled engineering attention—that would previously be devoted to commodity DRAM are instead allocated to HBM die and module production. The effect is not simply a reduction in the number of DDR wafers produced; it encompasses packaging and test capacity reallocation, workforce prioritization, and strategic prioritization of high-margin HBM projects that delays or reduces commodity output.
- Direct wafer reallocation: Foundry and IDM decisions to convert certain reticles and process flows to HBM-capable die reduce available wafer-equivalents for commodity DRAM.
- Packaging diversion: OSATs and in-house packaging teams prioritize HBM module production—especially hybrid-bond and interposer assemblies—shifting assembly capacity away from DDR module production lines.
- Engineering focus: Yield-engineering and fab resources get concentrated on complex HBM ramps, slowing incremental improvements or extensions for commodity DRAM nodes.
Because DRAM markets traditionally respond to lead times measured in quarters, even moderate reallocation can materially change near-term capacity balance and therefore pricing outcomes.
Why suppliers chose HBM over commodity DRAM
Several factors made HBM an attractive reallocation target for memory makers:
- Higher realized ASPs: HBM modules command significant premiums relative to wafer-equivalent DDR, improving revenue per wafer when wafer output is consumed as HBM die and finished modules.
- Margin stability: HBM buyers—hyperscalers, OEMs, and accelerator vendors—prefer contracted supply, reducing exposure to spot-market volatility that drags commodity DRAM margins.
- Strategic customer commitments: Large customers offered long-term contracts, co-investments, and prepayments in exchange for guaranteed allocation, reducing capex risk.
- Vertical integration benefits: Vendors that could capture packing and module integration revenues retained more value on each wafer-equivalent used for HBM.
These incentives tilted capital and operational decisions toward HBM despite its higher technical complexity and initial yield uncertainty.
Quantifying the capacity shift
Precise numbers vary by company and quarter, but several industry indicators paint a clear picture of the scale:
- HBM wafer-equivalent share rose from low single digits in 2022 to above 20% of DRAM wafer-equivalent starts by 2026 in some industry estimates, a multi-fold increase in just a few years.
- Packaging-capable OSAT lines for hybrid bonding and interposer-based modules were prioritized, reducing available module assembly cycles for DDR DIMMs and leading to temporary bottlenecks in module production.
- Major memory makers publicly reported higher proportions of capital allocated to HBM-capable tooling and packaging, signaling multi-year strategic shifts rather than short-term experiments.
Even if only a fraction of wafer starts migrate permanently, the effect on near-term DDR supply is magnified because DDR production is sensitive to short-term scheduling and inventory cycles.
How crowding out tightened DDR supply
The supply tightening mechanism works through several reinforcing channels:
- Reduced wafer starts for DDR immediately cut available bit supply, tightening the physical market for commodity modules.
- OSAT and test-house prioritization for HBM lowered throughput for DDR module assembly—creating downstream bottlenecks even when wafer supply was available.
- Inventory management shifted: suppliers held more finished HBM modules in backlog for strategic customers, reducing spot availability of DDR as buffers were drawn down.
- Engineering bandwidth constraints slowed the ramp of incremental DDR process improvements that might otherwise increase yields, further limiting supply growth.
These elements combined to reduce the elasticity of DDR supply to demand shocks, meaning price movements could be larger and more persistent than in prior cycles where suppliers could quickly add or reallocate capacity back to DDR.
Pricing impact on traditional DRAM
Market outcomes reflected the new supply dynamics in predictable and less obvious ways:
- Support for DDR ASPs: Against some analyst expectations of a steep price decline, DDR prices stabilized or even rose modestly in several 2025–2026 quarters due to reduced wafer flow and module throughput.
- Reduced downside volatility: Because a material share of DRAM capacity was now under long-term contracts (HBM and some DDR deals with hyperscalers), the spot market saw less extreme swings but also thinner liquidity.
- Channel tightness: Distribution channels for commodity DRAM experienced intermittent allocation as suppliers prioritized contract-bound, higher-margin customers.
- Upstream ripple effects: Higher DDR ASPs supported marginally improved gross margins for suppliers still selling commodity modules, improving short-term cash flow even as capex for HBM remained high.
In short, crowding out created a supply-side floor under DDR prices that would not have existed had all wafer-equivalents remained allocated to commodity outputs.
Winners and losers
The reallocation of capacity produced distinct winners and losers across the value chain.
Winners
- Major memory makers with HBM capability: They captured higher ASPs and blended-margin improvements as HBM volumes rose.
- Hyperscalers and OEMs with long-term agreements: Secured prioritized supply for high-performance modules and could plan infrastructure investments with less allocation uncertainty.
- OSATs and equipment vendors specializing in hybrid-bond and interposer manufacturing: Benefited from concentrated orders and higher utilization.
- Investors in vertically integrated firms: Blended margins improved as packaging and module revenue was captured in-house, supporting corporate cash flows during cyclical commodity downtimes.
Losers
- Small OEMs and channel buyers without strategic contracts: Faced intermittent allocations and price increases for commodity DRAM parts.
- Standalone DIMM makers dependent on third-party OSATs that were repurposed for HBM: Experienced capacity shortfalls and longer lead times for assembled modules.
- Late-stage entrants to HBM or small memory manufacturers: Struggled to compete with the Big Three’s capital and customer relationships in capturing the premium HBM market.
The net effect was a bifurcated market where well-resourced buyers and suppliers benefited while smaller players felt the pain of allocation and cost pressure.
Strategic responses from buyers and suppliers
Market participants adopted a set of predictable strategies to manage the new dynamics:
- Multi-year contracting: Buyers increasingly secured long-term agreements, prepayments, or capacity reservations to lock in supply and hedge against spot market volatility.
- Design flexibility: OEMs designed systems to accept alternative memory sources or to be tolerant of slightly different module specs, reducing supplier lock-in risk.
- Vertical integration: Some distributors and OEMs sought closer ties or minority investments in OSATs and packaging partners to preserve assembly access.
- Inventory management changes: Channel partners adjusted stocking policies—raising safety stocks at the cost of working capital to avoid allocation-induced shortages.
- Supplier differentiation: Smaller memory makers searched for niche segments (e.g., industrial DRAM, automotive-grade memory) less affected by HBM-driven reallocations.
These shifts moved the market toward contracted, less-liquid structures in which strategic relationships mattered more than spot pricing alone.
Macro risks and possible reversals
While crowding out strengthened DRAM prices in the near term, several scenarios could reverse the trend:
- Overinvestment in HBM and packaging capacity: If multiple players over-commit capex and packaging bottlenecks resolve faster than demand grows, finished-module supply could rise quickly and depress both HBM and, via cross-elasticity, DDR prices.
- Demand slowdown in AI capex: A marked pull-back by hyperscalers in training-cluster investments would reduce HBM demand, freeing capacity to return to DDR and pressuring DDR prices anew.
- Technological substitution: Innovations that provide comparable bandwidth at lower cost (new GDDR variants, on-chip caches, disaggregated memory interconnects) could reduce long-term HBM premiums and thereby influence allocation decisions.
- Policy shocks: Export controls affecting equipment or materials could abruptly curb HBM production, shifting suppliers back toward commodity DRAM but also raising costs and volatility during transitions.
The evolution of these scenarios determines whether crowding out is a temporary phenomenon tied to a specific demand cycle or a longer-term structural change in DRAM economics.
Implications for investors and financial modeling
Investors should update their DRAM-model assumptions to reflect allocation dynamics rather than relying solely on historical capacity elasticity assumptions. Practical modeling adjustments include:
- Explicitly modeling wafer-equivalent allocation by product tier (HBM versus commodity DDR) and scenario-testing how reallocations affect ASPs and gross margins.
- Incorporating packaging throughput constraints and yield ramps into near-term supply forecasts—finished-module supply is the true bottleneck, not just wafer output.
- Assessing counterparty risk: Companies with long-term HBM contracts will show different cash-flow profiles than pure commodity players; valuation multiples should reflect differences in revenue visibility and margin stability.
- Monitoring leading indicators: Capex announcements, OSAT equipment deliveries, backlog reports, and hyperscaler procurement plans provide early signals of allocation shifts.
Investors who capture the allocation dynamics early can differentiate winners—suppliers with integrated packaging and secured demand—from commodity-exposed players vulnerable to cycle swings.
Recommendations for stakeholders
Given the crowding-out environment, practical recommendations vary by stakeholder:
- Hyperscalers and OEMs: Secure long-term supply agreements and consider co-investment in packaging capacity; design systems to be flexible across memory types to reduce allocation exposure.
- Memory suppliers: Balance HBM and DDR investments carefully—capture high-margin HBM where strategic, but preserve commodity DRAM capacity to serve broader markets and avoid overexposure to a single demand stream.
- OSATs and packaging houses: Invest in hybrid-bond and interposer throughput but maintain a portion of capacity for commodity DDR module assembly to capture diverse revenue streams.
- Channel partners and smaller OEMs: Build stronger supplier relationships, increase safety stocks strategically, and pursue niche markets less sensitive to HBM reallocations.
- Policymakers: Encourage diversification of packaging and interposer capacity across allied regions to reduce concentration risk and protect critical compute supply chains.
Outlook: is crowding out permanent?
Whether crowding out becomes a permanent feature of the DRAM landscape depends on technological, commercial, and policy developments. If HBM remains essential to mainstream AI and HPC, and if long-term contracted demand grows, a sustained higher share of wafer starts to HBM is plausible. In that case, DDR markets will adjust structurally—higher base ASPs, greater importance of contracted supply, and a more segmented market between performance and commodity tiers.
Alternatively, if HBM premiums compress due to faster-than-expected packaging scale or substitution technologies emerge, then some of the repurposed capacity could be redirected back to DDR, restoring prior elasticity and cyclical dynamics.
Conclusion
The rise of HBM as a strategic product has had an unintended but predictable consequence: it crowded out some commodity DRAM capacity and, in doing so, supported DDR pricing and blunted the severity of an otherwise expected DRAM cycle downturn. The crowding-out effect underscores a broader lesson for semiconductor markets—capacity is fungible only up to a point, and the packaging, testing, and contractual ecosystem that links wafers to finished modules matters as much as fabs in determining final supply and price outcomes.
For market participants the practical task is to recognize allocation risk, secure supply through contracts and design flexibility, and model supply not as a single fungible pool but as a portfolio of product-driven allocations. The new dynamics reward players who can align wafer, packaging, and customer strategy coherently—and penalize those who treat capacity as infinitely convertible between product types.